What Really Happens During a Vehicle Pledge? A Borrower’s Walkthrough
Most car owners hear “bring your car” and stop there. The actual vehicle collateral loan process is more methodical. It protects both sides. Knowing the steps helps you prepare and avoids delays in Kano or Lagos.
ALHERI LENDING COMPANY LTD (CAC Registered: RC 9791563) follows a standard verification flow used by licensed Nigerian vehicle lenders.
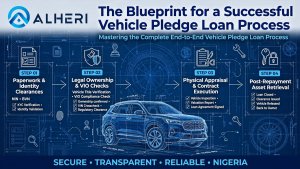
Step 1: Identity and Address Verification – NIN/BVN
First, identity. Not because lenders are curious. Because NDPA 2023 and anti-fraud rules require it.
You will be asked for:
- Valid NIN (National Identification Number) – primary ID.
- BVN verification – confirms you are the bank account holder for disbursement.
Why BVN? No hidden agenda. It ensures cash goes to the verified owner, not a third party.
Step 2: Proving You Own the Car Legally
This is where many applications pause. A car is movable property. Ownership must be airtight.
Required documents, as seen on professional checklists:
- Proof of Ownership (POC) / Vehicle Registration – Your name must match ID, or you must have transfer deed.
- Customs / Clearing papers and Purchase Agreement – Critical for fairly used imports. It proves no smuggling lien.
- VIO Road Worthiness Certificate – Shows car is road legal.
- CMR Police Theft Check (Central Motor Registry) – Confirms vehicle is not flagged as stolen. This is non-negotiable.
- Valid Insurance Papers – At least third-party.
If you bought the car from a friend in Sabon Gari without formal transfer, fix that first. No licensed garage will custody a car with cloudy title.
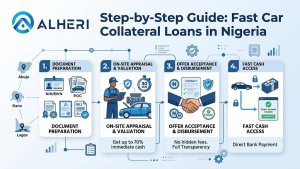
Step 3: Physical Condition Inspection, Not Guesswork
Appraisal is not “oga, how much?” It’s structured.
A trained inspector checks:
- VIN and engine number match documents.
- Odometer reading logged with photo. This is your baseline for zero unauthorized driving later.
- Exterior, interior, electronics, AC, mileage.
- Mechanical test – engine start, gear shift, suspension.
- Underbody for rust, especially important for Lagos humidity exposure.
The valuation then places your car in a bracket. ALHERI’s model, for example, funds 30-70% of assessed value. That Loan-to-Value (LTV) protects you from over-leverage.
Step 4: Contract Review – Where Borrower Rights Live
Here is where DEON matters most. Don’t rush.
Read for:
- Exact tenure. Vehicle pledge is short-term, usually up to 3 months. Not 2 years.
- Storage location and security standard. Should state “24/7 guarded, CCTV-monitored secure garage” and that mileage will not increase except for in-garage movement.
- Fees broken down. No lump sum “charges.”
- Default and notice period. How many days after due date before action? What is cure process?
- Data privacy clause. Reference to NDPA 2023, purpose limitation.
Short process, yes. 30 minutes cash after signing is possible, but only if your documents are complete before you walk in. Prepare them.
Have Questions About Your Car Value?
Get a free instant vehicle appraisal on WhatsApp from our team.