Decoding Borrower Rights When You Take a Loan Against Car Equity
The financial terrain of urban Nigeria pulses with energy, yet navigating credit markets requires absolute clarity regarding legal protections. When private motorists, transporters, and enterprise owners across the commercial heartbeat of Lagos or the trade hubs of Kano take loan against car assets, understanding federal guardrails transforms a complex financial transaction into a secure, predictable experience. Modern asset-backed lending operates under stringent regulatory oversight designed specifically to shield consumers from opaque terms and predatory traps. At ALHERI LENDING COMPANY LTD (CAC Registered: RC 9791563), institutional compliance is not merely a formality—it is the bedrock of every transparent client engagement.
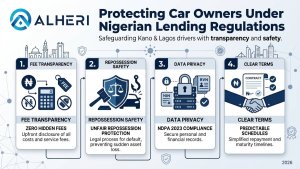
Consumer empowerment begins with the active enforcement of guidelines established by the Federal Competition and Consumer Protection Commission (FCCPC). Historically, informal credit channels were plagued by hidden charges, shifting interest computations, and sudden penalties. Today, licensed institutional lenders must provide absolute pricing transparency upfront. Every fee, service charge, and repayment milestone is laid bare before pen meets paper. This regulatory environment ensures that you can evaluate your credit options with mathematical precision, completely free from the anxiety of unannounced financial liabilities.
Safeguarding Digital Identity and Personal Data
In an era where digital footprints expand daily, data privacy remains a non-negotiable priority. Submitting personal documentation—such as your National Identification Number (NIN) and Bank Verification Number (BVN)—demands rigorous institutional security. Under the Nigeria Data Protection Act (NDPA) 2023, licensed financial providers bear a legal obligation to manage consumer records under strict cryptographic standards.
ALHERI LENDING COMPANY LTD deploys multi-layered data encryption protocols to isolate and protect borrower identities. Unauthorized commercial sharing, data harvesting, or third-party profiling are strictly prohibited by federal law. Consequently, every borrower retains the statutory right to audit their stored profile, verify data usage, and operate with total assurance that their personal privacy stays shielded throughout the credit lifecycle.
Lawful Asset Custody Versus Predatory Repossession
Misconceptions frequently surface regarding how physical collateral is managed during a secured loan tenure. Informal markets have sometimes given rise to unsanctioned vehicle usage or aggressive, informal recovery tactics. However, licensed collateral lending adheres to uncompromising ethical custody standards. Operating or test-driving a client’s pledged vehicle is strictly unlawful.
Professional lenders maintain dedicated, climate-protected, and 24/7 CCTV-monitored facilities where vehicles remain undisturbed from the initial intake day to final redemption. Before placement, an exhaustive condition report records exact mileage and physical aesthetics. This rigorous documentation guarantees that your vehicle experiences zero depreciation or unauthorized transit, ensuring it returns to you in the exact condition it was entrusted.
Have Questions About Your Car Value?
Get a free instant vehicle appraisal on WhatsApp from our team.