Clarifying Core Inquiries Regarding a Vehicle Asset Backed Loan
Navigating asset-backed liquidity often raises practical questions regarding custody mechanics, repayment structures, and term safety. For motorists across bustling economic centers like Lagos and Kano, institutional transparency forms the bedrock of sound financial planning. When evaluating a vehicle asset backed loan, understanding the operational differences between paper title retention and physical garage custody—alongside disciplined repayment strategies—empowers borrowers to make highly informed decisions.
At ALHERI LENDING COMPANY LTD (CAC Registered: RC 9791563), consumer education is a core institutional commitment. Below are direct, authoritative answers to the most frequent inquiries raised by Nigerian car owners seeking transparent vehicle-backed credit solutions.
Paper Title Liens Versus Physical Secure Garage Custody
A frequent point of discussion involves whether leaving vehicle documentation with a lender is preferable to placing the physical vehicle in secure custody. Many wonder why professional lenders require physical possession of the automobile.
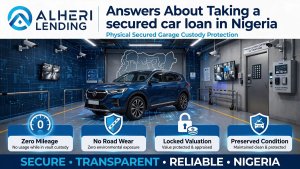
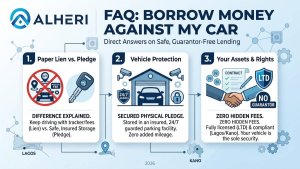
Physical vehicle custody provides superior operational security compared to simple paper title liens. By maintaining the physical asset in a locked, insured, 24/7 CCTV-monitored facility, lenders eliminate dual-pledging risks and title fraud. This tangible security allows licensed institutions to offer highly competitive interest rates and rapid approvals without invasive, multi-week credit bureau investigations.
Safeguarding Assets and Preventing Debt Cycles
- How is my automobile protected while in custody? Vehicles rest in secure, roofed enclosures with restricted personnel access. Odometer readings, fuel levels, and exterior states are logged precisely at intake to ensure zero unauthorized movement or mileage accumulation.
- What safeguards prevent long-term debt entanglements? Short-term asset-backed credit is intentionally engineered for temporary liquidity needs—such as enterprise cash flow bridging or urgent commercial capital. Establishing realistic, short-term repayment timelines ensures borrowers redeem their vehicles swiftly without compounding interest burdens.
- Are there penalties for early loan settlement? Transparent lending practices encourage early redemption. Borrowers can settle their balances ahead of schedule without facing punitive prepayment penalties, ensuring total flexibility and control over their personal finances.
Have Questions About Your Car Value?
Get a free instant vehicle appraisal on WhatsApp from our team.