Understanding your rights before signing a car financing or vehicle-secured loan agreement helps you identify unclear charges, protect your personal information and respond appropriately to repayment disputes. In Kano, Lagos and other Nigerian cities, borrowers should understand the applicable consumer-protection rules and distinguish between general legal rights and protections that depend on the lender and facility.
What Nigerian Consumer Lending Regulations Mean
The Federal Competition and Consumer Protection Commission (FCCPC) administers consumer-protection rules, including the Digital, Electronic, Online or Non-Traditional (DEON) Consumer Lending Regulations 2025. The framework addresses transparency, accountability and unfair lending practices within its scope. It should not automatically be treated as applying identically to every traditional or vehicle-secured loan.
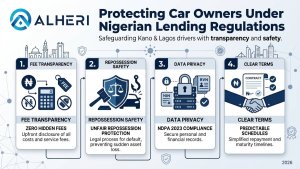
Demand clear disclosure of charges
Before accepting an offer, ask for a written breakdown of the total repayment obligation. It should explain:
- The principal amount you will receive.
- Interest and every applicable administrative or processing fee.
- The repayment deadline and accepted payment method.
- Late-payment charges, when applicable, and how they are calculated.
- Conditions for releasing your vehicle after repayment.
A statement such as “no hidden charges” is not a substitute for a complete written agreement. If a charge is introduced after signing, request the contractual basis and a written explanation. Do not assume every additional charge is lawful simply because it appears on an invoice.
Vehicle Recovery and Fair Debt Practices
A vehicle pledge may involve physical custody rather than a lender holding only a document or recording a security interest. The agreement should clearly explain the custody arrangement, default conditions, notice procedures and the steps available if repayment becomes difficult.
Borrowers should not assume that a missed payment automatically authorises every form of repossession or recovery action. Nor should they assume that all enforcement requires identical court procedures. The answer depends on the contract, applicable law and circumstances.
Keep payment receipts and written communications. If a dispute arises, request an account statement and the lender’s explanation before accepting an unexplained balance.
Protecting Your Personal Data
The Nigeria Data Protection Act 2023 establishes rules for lawful and accountable personal-data processing. Depending on the circumstances, individuals have rights relating to information, access, correction, objection and complaints.
Before submitting your National Identification Number (NIN), Bank Verification Number (BVN), address or vehicle records, ask why each item is needed, how it will be used, who may receive it and how it will be protected. Do not share passwords or one-time security codes.
A lender should not treat access to a customer’s contact list as permission to expose private information or harass unrelated people over a debt.
Have Questions About Your Car Value?
Get a free instant vehicle appraisal on WhatsApp from our team.