A Comprehensive Guide to Vehicle Financing and Asset Pledging
Securing short-term liquidity using an automobile asset offers a fast, accessible financial solution for Nigerian motorists without requiring third-party guarantors. Whether located in the bustling commercial corridors of Lagos or the vibrant markets of Kano, car owners can leverage their vehicle equity efficiently. Understanding the required paperwork, physical inspection protocols, and contractual obligations ensures a smooth, transparent borrowing experience from start to finish.
Required Documentation Checklist for Loan Approval
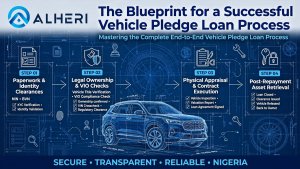
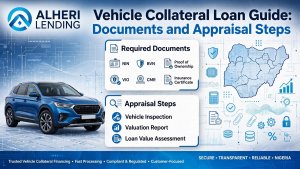
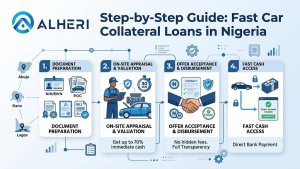
Before initiating a vehicle financing application, borrowers must assemble a complete set of legal verification documents. Licensed lending institutions require these records to confirm ownership identity, roadworthiness, and security clearance:
- Valid Identification: National Identification Number (NIN) slip and Bank Verification Number (BVN) confirmation.
- Proof of Residence: Recent utility bill covering the past three months.
- Ownership Proof: Original Proof of Ownership Certificate (POC) or official vehicle registration papers.
- Regulatory Clearance: Valid VIO roadworthiness certificate, CMR police theft check report, and comprehensive insurance documents.
- Acquisition Records: Original purchase agreement or customs clearing paperwork where applicable.
Vehicle Inspection and Valuation Standards
Once documentation is verified, the physical appraisal takes place on-site. Professional appraisers evaluate the automobile’s mechanical health, interior condition, body panels, and current market value. Lenders typically disburse between 30% and 70% of the assessed vehicle value, ensuring the loan amount remains safe and manageable. The appraisal is objective, fast, and transparent, allowing successful applicants to receive cash funds within 30 minutes of contract finalization.
Secure Garage Custody and Contract Review
A defining feature of licensed vehicle collateral arrangements is physical asset custody. Unlike paper title loans where ownership titles remain at risk, physical pledge models require the car to be safely parked in a monitored 24/7 CCTV garage for the loan duration. Borrowers review the agreement terms—including short repayment windows up to 3 months—ensuring complete clarity on principal, interest, and release protocols. Upon final loan settlement, the vehicle is promptly returned in its exact inspected condition.
Have Questions About Your Car Value?
Get a free instant vehicle appraisal on WhatsApp from our team.